A crowded airport terminal and a nearly full aircraft are often interpreted as signs of a successful airline industry.
Yet passenger demand and financial profitability do not always move in the same direction.
An airline may carry millions of passengers, operate a substantial international network and achieve high seat occupancy while generating only a modest financial return.
The distinction has become particularly important in 2026, as airlines confront rising operating costs, geopolitical disruptions and continued pressure on aircraft availability.
Strong Demand, Weaker Returns
In its June 2026 financial outlook, the International Air Transport Association (IATA) projected that global airlines would generate a combined net profit of US$23 billion for the year.
That represented a substantial downward revision from its earlier forecast of US$41 billion.
The industry’s expected net profit margin fell to 2%, compared with an estimated 4.2% in 2025.
IATA also projected average net earnings of approximately US$4.50 per passenger.
These figures illustrate the limited financial cushion available to airlines despite the scale of global air transport.
Why Full Aircraft Are Not Enough
Airline profitability depends on more than the number of occupied seats.
The revenue earned from each passenger must be sufficient to cover fuel, labour, aircraft financing, maintenance, airport charges, navigation fees and other operating expenses.
A flight can achieve a high passenger load factor and still produce a weak financial result if ticket revenue does not adequately cover its costs.
Similarly, increasing flight frequencies may improve market presence without necessarily improving profitability.
The commercial objective is therefore not simply to fill aircraft, but to generate sustainable revenue relative to the cost of operating each service.
Fuel Remains a Major Financial Risk
Fuel prices are among the most significant variables affecting airline economics.
IATA’s June outlook identified a sharp increase in jet fuel costs linked to the Middle East conflict as a major contributor to the deterioration in industry profitability.
Higher fuel expenditure can affect airlines differently depending on their networks, aircraft efficiency, fuel purchasing arrangements and exposure to disrupted airspace.
Longer flight routings may further increase consumption and operating time.
Airlines can attempt to recover additional expenses through fares and ancillary charges, but competitive conditions and passenger demand influence how much of those costs can be passed on.
The Cost of Limited Aircraft Availability
Fleet constraints create another layer of financial pressure.
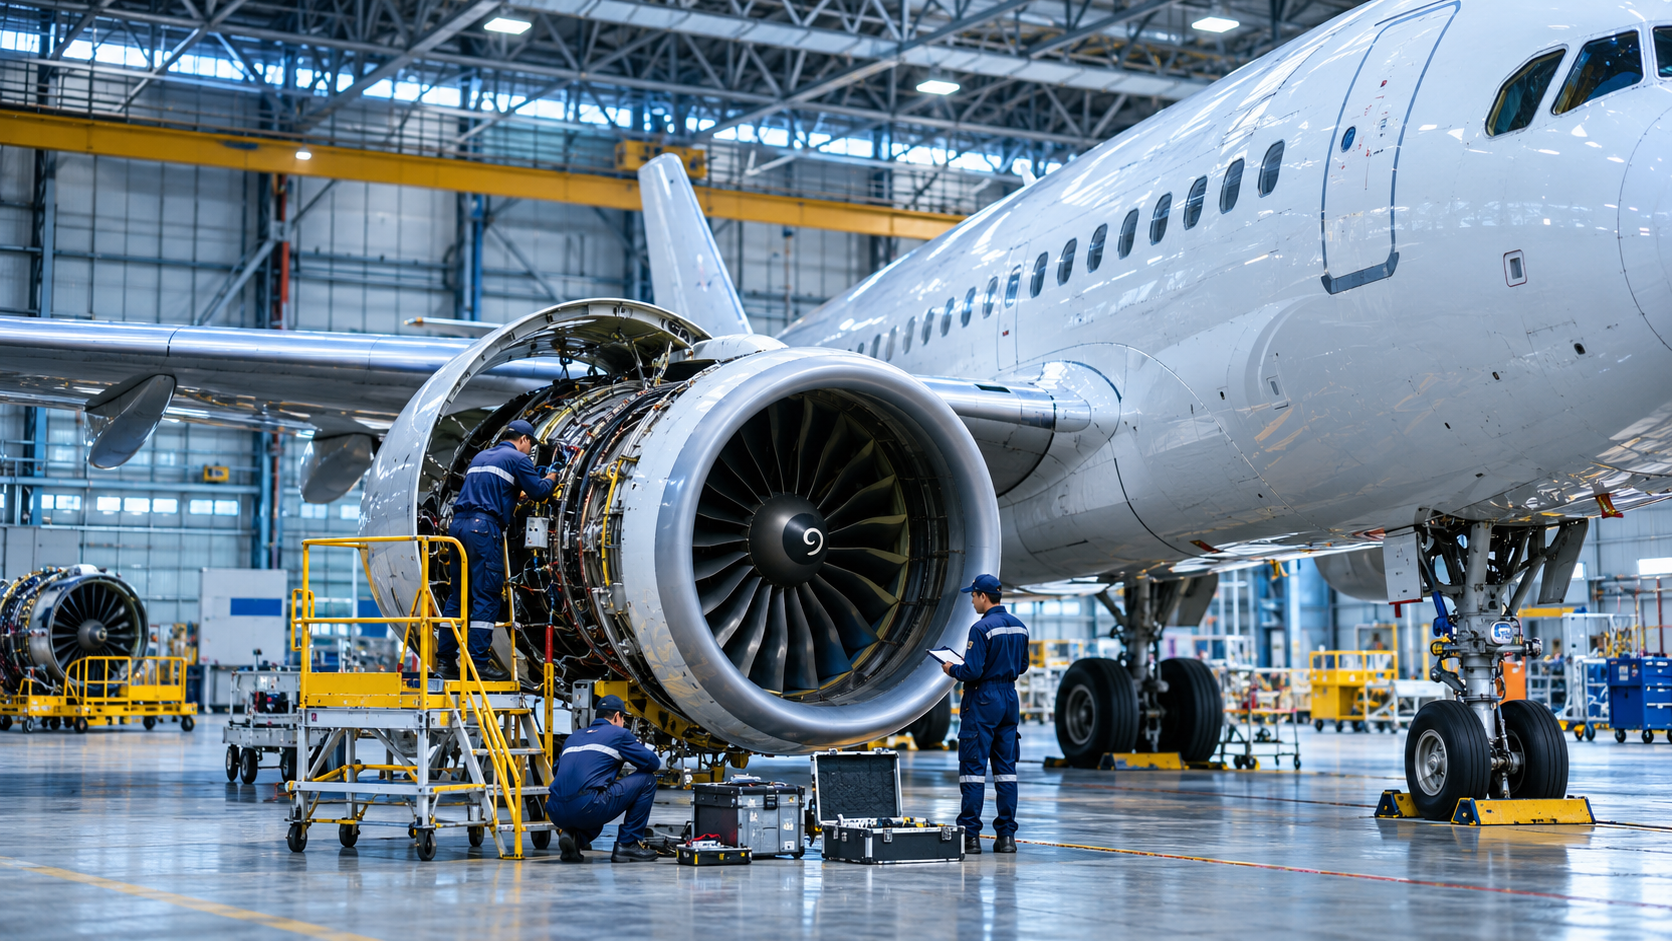
When aircraft deliveries are delayed or engines require extended maintenance, airlines may have to retain older aircraft, extend leases or obtain replacement capacity.
These arrangements can increase expenditure while limiting an airline’s ability to expand services.
Maintenance disruptions can also reduce the operational flexibility needed to respond to changing demand.
For carriers operating on narrow margins, additional costs or prolonged aircraft downtime can materially affect financial performance.
Different Regions, Different Outcomes
The financial outlook is not uniform across global aviation markets.
IATA’s June forecast projected a combined net profit of US$6.6 billion for Asia-Pacific airlines in 2026, compared with an estimated US$9.8 billion in 2025.
The Middle East faced a more severe outlook because of regional conflict and operational disruptions.
These differences demonstrate why global passenger demand cannot be used as a single measure of airline financial health.
Regional exposure, operating structures and market conditions remain important determinants of profitability.
Growth Must Be Financially Sustainable
For airline management, the challenge is to distinguish between commercially attractive expansion and growth that creates additional financial exposure.
New routes, aircraft acquisitions and higher frequencies can strengthen a network, but each decision introduces operating commitments.
Financial sustainability requires careful consideration of route economics, fleet utilisation, cost control and the ability to withstand unexpected disruption.
The same principle applies to emerging airlines seeking to establish themselves in competitive markets.
Ambitious growth plans must be supported by realistic financial assumptions and sufficient operational resources.
The Bigger Picture
The airline industry remains essential to international trade, tourism and economic connectivity.
However, its importance does not guarantee strong returns for the companies providing those services.
IATA’s 2026 outlook reinforces a longstanding industry challenge: airlines operate businesses with substantial capital requirements and significant exposure to costs beyond their immediate control.
The central question is no longer whether people want to fly.
It is whether airlines can meet that demand while earning enough to maintain their fleets, invest in future operations and remain financially resilient.
Full aircraft may demonstrate commercial demand. Sustainable profitability requires considerably more.